Commercial Solar & Renewable Finance
ASM Money finance solutions are designed specifically for renewable energy, and with our industry experience, we can provide finance solutions that can be up to 20% more effective than using your own cash.
What are your Commercial Financing Options?
Does your client need funding before making a purchasing decision? Don't let upfront costs be a barrier to a sale. We help you offer accessible finance options, turning "maybe" into "yes."
Other than paying cash, there are five main options:
Power Purchase Agreement (PPA)
Managed Solar Operating Lease
Solar Finance Operating Lease
Chattel Mortgage
Equipment Line
Power Purchase Agreement (PPA)
With a PPA, no capital is required, allowing you to invest your cash elsewhere in the business while enjoying all the benefits of commercial solar.
An agreed price per kilowatt produced is set. This is typically 25% to 50% below the current grid price.
A PPA does not appear on your balance sheet and does not result in a credit application or credit hit. This allows you to maintain the highest capacity to raise capital and to finance with debt. A PPA is treated as an operational expense and is fully tax-deductible.
A PPA fully protects you against performance and operational risks. If a component fails or underperforms, we handle everything for you, including all repairs. The bottom line? No capital risk, no performance risk, and no product risk.
A commercial solar PPA is designed to deliver a service with a delivery guarantee as robust as the grid, at a commercially viable and predictable price point.
Managed Solar Operating Lease
Most businesses just want solar to produce usable power without fail.
This option is a fully managed operating lease, similar to a PPA, with a fixed monthly payment. Your solar system is monitored 24/7 by a dedicated customer service desk. Our service provider is one of the largest in Australia, and when a system falls below specification, it is promptly rectified. This includes insurance, panel cleaning, and any required servicing to ensure long-term system performance in line with the specification.
Solar Finance Operating Lease
This option is for a business prepared to manage the solar installation and its risks.
There are two main reasons why a solar finance operating lease is the most common finance solution for commercial solar installations.
- It is an ‘income-producing’ asset, and
- Solar is considered a long-term investment and is treated by the Australian Tax Office in a similar category to a roof replacement and must be depreciated over 20 years.
With a solar finance operating lease, 100% of your payments, like your electricity bill, are tax-deductible.
Ownership of the asset remains with the financier until the end of the lease, with options to purchase the goods available. Under IFRS 16, only the payment commitment appears on your balance sheet.
For a detailed discussion on finance types please read the article “Moving Away From the Gold Plated Grid” published in the 14 June 2018 Ecogeneration journal.
Chattel Mortgage
With a chattel mortgage, you take ownership of the solar asset immediately and add it to your asset register, providing the finance company with a mortgage over the asset.
As the amount financed includes the full amount, including GST, the consequent payments tend to be slightly higher than a Solar Finance Operating Lease.
Payments are NOT tax-deductible. Only interest and depreciation are tax-deductible, and under the ATO's rules for solar depreciation over 20 years, a chattel mortgage can be expensive.
The main attraction of this style of finance is the big cash ‘GST hit’ in the quarter you purchase the asset. Your client claims 100% of the GST paid on the purchase price in their next BAS statement, receiving a GST refund that can cover three or four monthly instalments, or is sometimes used to pay down the loan.
The only exception in which a chattel mortgage is ideal for solar is when a business qualifies for the instant asset write-off of up to $20,000, which was made permanent in the 2026 government budget.
Equipment Line
This is a variation of a chattel mortgage in which a business is provided a line of credit to install solar and purchase other assets, up to the facility limit.
SOLAR FINANCE IS MUCH MORE THAN AN INTEREST RATE
The first question we are typically asked is “What is your interest rate?”
While the interest rate is an important part of a finance package, selecting the right commercial finance product to meet the business's financial needs is equally important.
Here are two examples of how an ASM Money finance consultant crafted a ‘fit-for-purpose’ solar finance solution tailored to a customer’s needs.
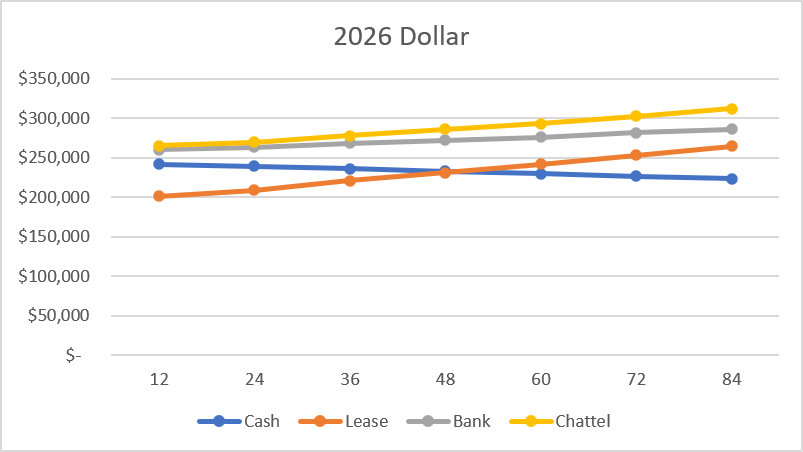
One Year Lease – up to 20% less than cash
A major sale was delayed for nearly a year while the client needed the expense approved and added to the Capex budget the following year. We worked with the client and showed them that a one-year operating lease would save nearly 20% of the cash price, with the savings available today rather than in 12 months' time.
Here are the magic numbers for a tax-paying business. All numbers are ex-GST.
| | 12 mths term | 24 mths term | 36 mths term | 48 mths term | 60 mths term | 72 mths term | 84 mths term |
|---|---|---|---|---|---|---|---|
| Cash | $241,938 | $238,875 | $235,813 | $232,750 | $229,688 | $226,625 | $223,563 |
| Lease | $201,401 | $208,628 | $220,566 | $231,057 | $241,852 | $252,950 | $264,346 |
| Bank | $259,875 | $262,972 | $267,983 | $272,257 | $275,708 | $281,245 | $285,957 |
| Chattel | $264,791 | $269,644 | $277,840 | $285,818 | $293,065 | $302,697 | $311,594 |
Note:
Financed rates are estimates based on 1 Aug 2026 rates and may change at any time
Tax rates based on company tax for turnover <$50 million
Subject to credit approval
This is general advice only, based on a profitable trading entity.
Fruit Growing Business
This Riverland fruit-growing business had been trading well and was generating significant profits, resulting in a potentially very large tax liability for the current year. All indications were that the following year was going to be even better. They were tempted to pay cash to install solar.
The ASM Money consultant noted that, given the slow rate of depreciation allowed by the tax office, a short-term solar finance operating lease (2 years) was probably a better option and would deliver significant tax benefits. They recommended he take out an operating lease for the system over two years and pay annually in advance. The grower was already planning to pay cash, so this was simply a change in how they would pay it.
This simple change took the $85,000 solar array, after accounting for all tax benefits, to a cash outlay of $57,811 over ten years, while paying cash up front would cost $65,681 over the same period. Even better, the cash payments were now 100% tax-deductible, saving the grower an enormous tax bill.
As rural production can be highly uncertain, this also preserved cash for the following years, when uncertain weather patterns might put pressure on the business.
Just as important was timing. The finance had to settle by 30 June, and it was already the end of May. Using our ‘low doc $150,000’ facility, approval was completed the same day, documents were finalised, and installation commenced, so settlement could occur on 28 June. A further two days’ delay would have meant they could say goodbye to this year’s tax write-off and would have ended up paying company tax on a very large sum of cash!
#ASM Money are not financial advisors and recommend that you seek independent accounting advice regarding financial products and the new IFRS 16 accounting standards.